Using Long-Term Care Insurance for Home Care in Atlanta: What Actually Happens
Most long-term care insurance policies cover in-home care, not just nursing homes — but families rarely know how to start a claim. Here is how long-term care insurance works with home care services in Atlanta and across Georgia.
October 8, 2026 · 3 min read
If a parent has long-term care insurance, there is a good chance it covers home care — not just a nursing home. Most families never find out, because nobody tells them and the policy is in a drawer somewhere from 2004.
Here is how long-term care insurance and home care services in Atlanta actually fit together, and what to do first.
Does long-term care insurance cover in-home care?
Usually, yes. Policies written in the last twenty-five years nearly always include home and community-based care, often at the same daily benefit as a facility. Older policies are more mixed — some are facility-only, some pay home care at a reduced rate.
The only way to know is to read the policy, or to have somebody read it with you. The section you want is usually called *covered services* or *benefit eligibility*.
What usually triggers the benefit
Most long-term care policies pay out when one of two things is true:
- The person needs hands-on or standby help with at least two activities of daily living — commonly bathing, dressing, toileting, transferring, continence and eating.
- Or there is a cognitive impairment, such as Alzheimer's or another dementia, that means they need supervision for their own safety.
A doctor or a nurse usually has to certify this. Insurers also generally require a written plan of care, which is one of the reasons we have a Registered Nurse write and review every plan we produce.
The elimination period is the part that catches people out
Nearly every policy has an elimination period — a waiting stretch, commonly 30, 60 or 90 days, during which you pay privately before the insurer starts paying.
Two things families get wrong here:
- Some policies count calendar days and some count days of paid service. A 90-day elimination period on three visits a week is a very different wait from 90 calendar days.
- The clock usually does not start until care actually begins. Waiting to start care means waiting to start the clock. Families who delay three months to "see how things go" simply move their coverage three months later.
Who the insurer will pay
Most policies require a licensed home care agency. Some will cover an independent caregiver; many will not, and some exclude family members outright.
Healthcare Support Home Care is licensed, bonded and insured in the state of Georgia, and our caregivers are background-checked and trained before they start. We can provide the documentation insurers ask for.
How the money actually moves
Two arrangements are common:
- Reimbursement. The family pays the agency, submits invoices and visit records, and the insurer reimburses. Most policies work this way.
- Assignment of benefits. The insurer pays the agency directly. Not every policy allows it, and it usually has to be set up in advance.
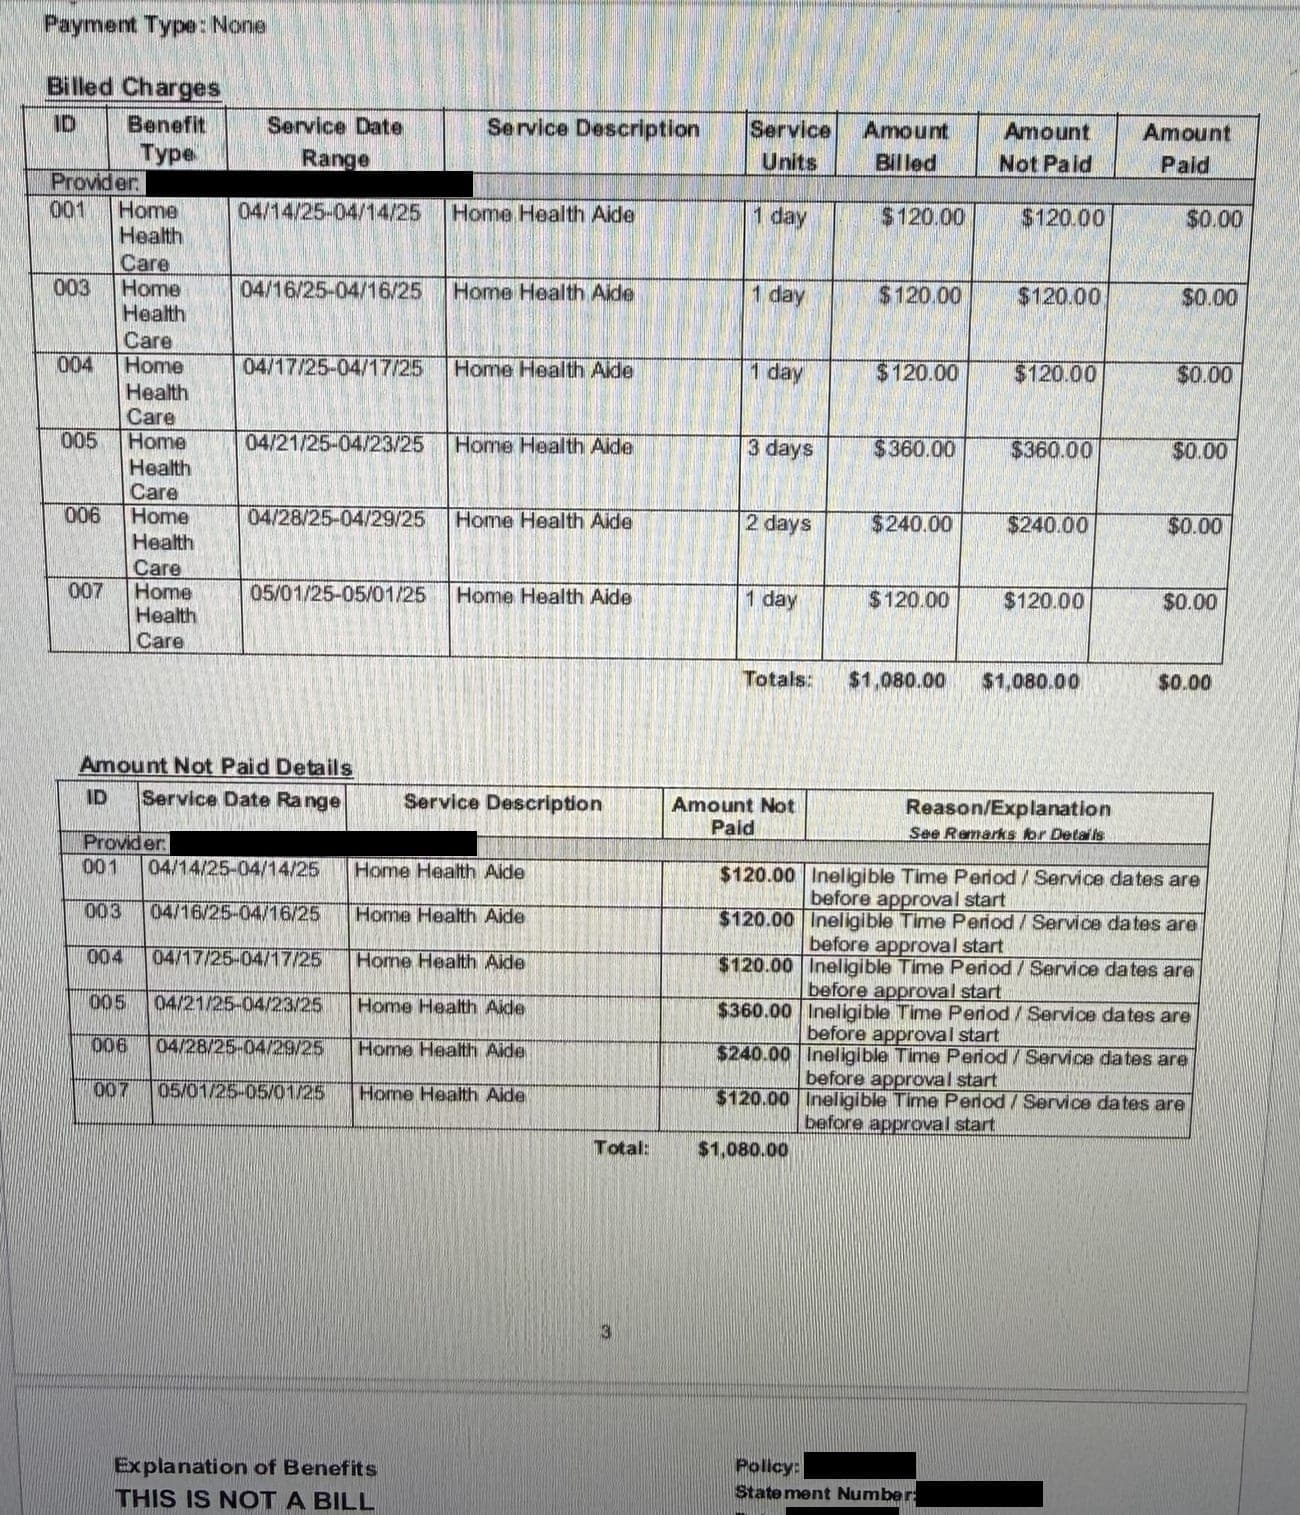
Either way, the paperwork matters: dated visit records, the tasks performed, the caregiver's name, the hours. We keep that documentation as a matter of course, because a claim denied on missing records is an expensive way to learn the lesson.
What to do this week
- Find the policy and note the daily or monthly benefit, the elimination period, and whether there is inflation protection.
- Ring the insurer's claims line and ask what they need to open a claim.
- Ask the doctor about certification for the activities of daily living.
- Start care when you need it, not when the paperwork is finished.
Home care across metro Atlanta and twenty Georgia counties
We serve families across metro Atlanta — Fulton, DeKalb, Cobb, Gwinnett, Clayton, Cherokee, Douglas, Henry, Fayette, Coweta, Rockdale, Newton, Forsyth, Carroll and more — and out to Macon and Savannah.
If you are holding a policy you do not understand, bring it to the conversation. We will tell you honestly what we can see in it, and what you need to ask your insurer.
(404) 375-7808
Wondering whether the Medicaid waiver could cover care for your family?
Check in two minutes